
Four earnings nights compared with one-second records
A comparison of stored one-second perpetual-futures reference prices around four earnings filings: NVDA, MRVL, DELL and AVGO.
INDEX
Prices and perpetual-futures definitions.
11 articles
A comparison of stored one-second perpetual-futures reference prices around four earnings filings: NVDA, MRVL, DELL and AVGO.
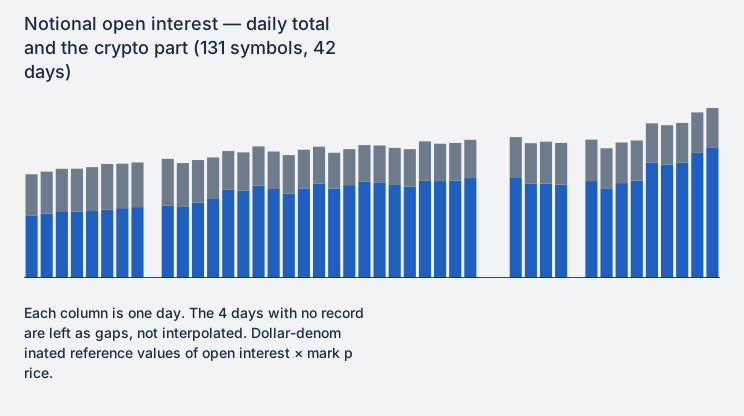
The public API keeps no history of open interest, so StockTicker24 records a snapshot every day. Across the 131 symbols recorded on all 42 days, the notional total ran from $9.98B to $16.37B and crypto's share from 60.4% on the first day to 76.5% on the last.
SHEIN listed on HKEX on Sep 1, 2026 under stock code 625. This explainer covers how to read the pre-listing reference value and how the display works after listing.
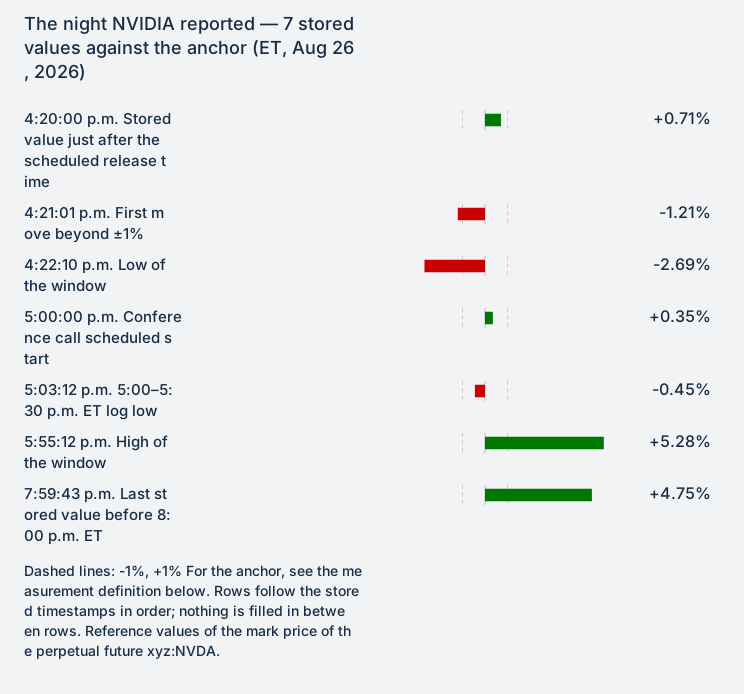
NVIDIA scheduled its results for approximately 4:20 p.m. ET on Aug 26, 2026 (approximately 1:20 p.m. PT), 20 minutes after the U.S. cash close. The perpetual-futures reference price is measured with one-second and 30-second logs.
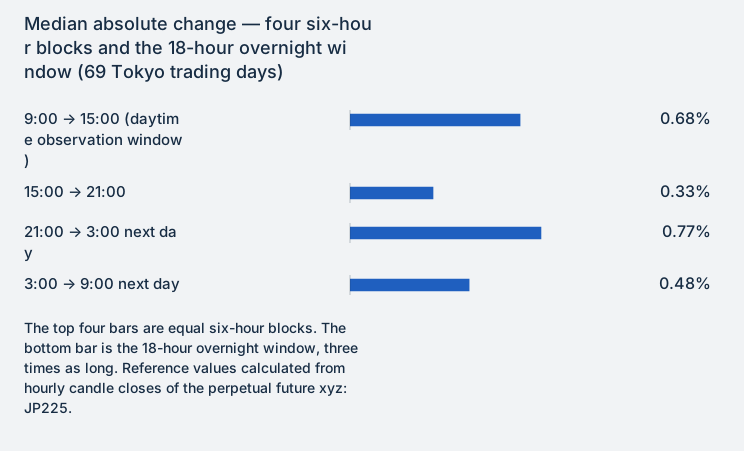
The daytime observation window is six hours; the other 18 are overnight. Across 69 Tokyo trading days on perpetual-futures reference prices, the median absolute change was 1.08% over the 18 overnight hours and 0.33% to 0.77% across four six-hour blocks.

Perpetual-futures reference prices also move at weekends. Across six symbols and up to 30 weekends, the Nikkei 225 cash-market window (Friday 15:00 → Monday 9:00) went beyond ±1% on 9 of the 18 weekends that fell between Tokyo trading days.
A perpetual future referencing Anthropic, a private company, has carried a 24-hour price since 19 August 2026. Under the issuer's specification $1 of the contract stands for $1B of market capitalization — what that scale means, and how it sits beside the announced valuation.

How perpetual futures and funding work, with saved contract counts, mark-to-oracle price gaps and weekend trades. Figures describe the recorded samples.
Saved S&P 500 perpetual-futures bars: six 50-hour weekends, trades by UTC hour and daily reference-price gaps, with the sample periods and calculation methods.

The VIX is calculated from S&P 500 option prices and is an annualised volatility figure covering a 30-day period. What it is calculated from, the period, the unit, and how it differs from this site's reference values.
Read the price, its comparison basis, missing values, open-interest mode, session lines and retrieval status on a StockTicker24 card.
Read next: Four earnings nights compared with one-second records